Big Year? Here’s How to Keep More of It: 2026 Year-End Tax Planning for High Earners
A big income year can come from a lot of places. A promotion. A fatter bonus. Company stock finally vesting. A business that had its best year yet. Or you sold something and it paid off.
By Connor Low
A big income year can come from a lot of places. A promotion. A fatter bonus. Company stock finally vesting. A business that had its best year yet. Or you sold something and it paid off.
Congrats. Now the less fun part. What you earned is only half the story. What you actually keep, what you need to set aside, and which moves are still on the table before December 31 are the parts that matter.
For high earners and business owners, year-end tax planning should not be a scramble for last-minute deductions. It should connect your comp, your investments, your retirement savings, your giving, and your business decisions into one plan. That is how we do it at Iarann Wealth, with a CFP, an EA, and a CFA all working the same file, and your accountant looped in before anything gets filed.
It matters more than usual in 2026. The deduction rules and retirement contribution rules changed, and a few strategies that worked last year will not work the same way. The goal is not the smallest possible tax bill. It is making smart decisions that leave you in a better spot after taxes.
Start With a Projection, Not Last Year’s Return
Last year’s return is a decent starting point. It is not a plan. If your income jumped, it is barely even a reference.
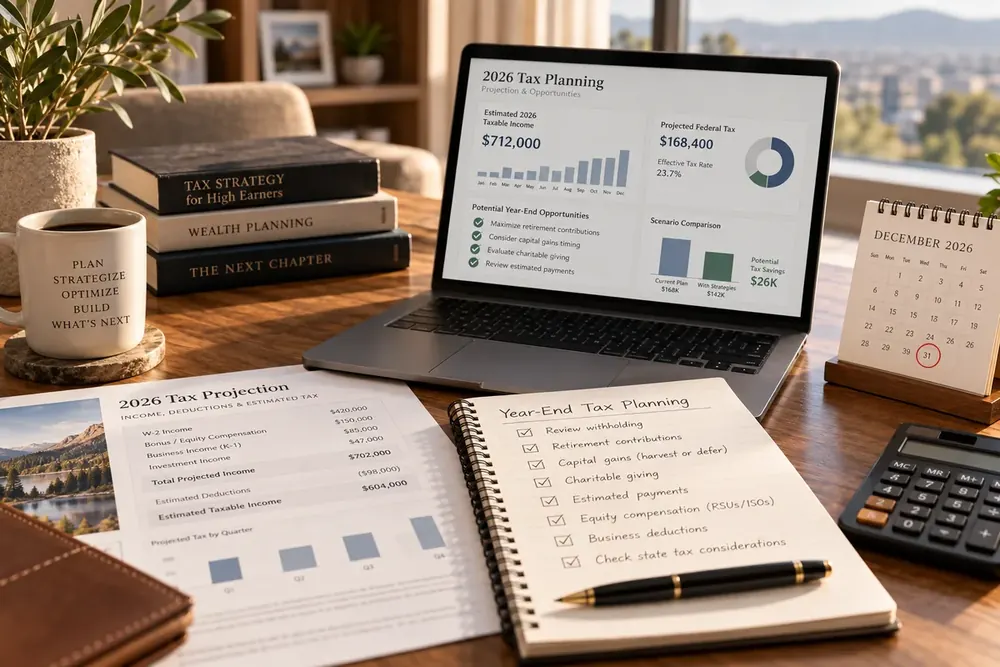
Before you sell anything, bump a retirement contribution, or write a check to charity, you need a projection of your full-year income and deductions. That is the first thing we build for every client in the fall, and nothing gets decided until it exists.
It pulls together your latest pay stubs, expected bonuses, equity comp records, realized gains and losses, business financials, and estimated payments made so far. If you are married, both of you go in the same model. Half a household is not a projection.
A real projection also goes past regular federal income tax. It checks the net investment income tax, the alternative minimum tax, and state. Those are the ones that blindside people, and they change how much you need to have paid in during the year.
When it is done, it answers three questions. What do you expect to owe in total? How much have you already paid? And which decisions still left this year could actually move the number?
It should also tell you whether this is a one-off spike or a new normal. A one-time stock sale calls for a different playbook than a permanent raise. Knowing which one you are dealing with changes everything downstream.
Your Bonus Withholding Is Probably Short
Taxes were withheld. That does not mean enough was withheld. These are different sentences, and the gap between them is where April surprises come from.
Most employers withhold a flat 22% federal rate on bonuses and other supplemental wages. That is a withholding shortcut, not a special bonus tax rate. Your bonus is taxed at your real marginal rate. (Supplemental wages over $1 million in a year get a different rule, but if that is you, call us.)
Quick example. You get a $100,000 bonus and $22,000 is withheld for federal income tax. If that bonus is actually taxed at a 35% marginal rate, the real federal tax on it is $35,000. You are $13,000 short before we even talk about state tax, payroll tax, or anything else.
Same deal after a big RSU vest or option exercise. Do not assume payroll handled it. We compare what was actually withheld against the household’s projected liability, line by line.
There is also a difference between avoiding a penalty and paying what you owe. For most high earners, the federal safe harbor is the smaller of 90% of this year’s tax or 110% of last year’s tax, paid on time through the year. The 110% version generally kicks in when your prior-year adjusted gross income was over $150,000. Hitting that safe harbor keeps the penalty away. It can still leave you with a large check due in April.
One useful quirk: federal withholding is treated as if it came in evenly across the year, no matter when it actually happened. So cranking up withholding on your last few paychecks can patch an earlier shortfall. A late estimated payment does not get that treatment. It only covers the period it was paid in. That is why we fix withholding in November, not estimates in January.
The Bigger SALT Deduction Is Not as Big as the Headline
The state and local tax deduction, or SALT, got a lot bigger. You have probably heard the number. The 2026 cap is $40,400. Here is the part you probably have not heard: that cap shrinks once your modified adjusted gross income passes $505,000, and it can fall all the way to $10,000.
So for a lot of the people reading this, the headline number is not your number.
Example. A married couple filing jointly has $600,000 of modified AGI. They are $95,000 over the threshold. The cap drops by 30% of that overage, which is $28,500. Their SALT cap is $40,400 minus $28,500, or $11,900. Not $40,400. And that is before checking whether they paid enough eligible state and property tax to use it, or whether they itemize at all.
This creates a trap we watch for closely. An extra bonus, a big capital gain, or a strong year in the business does not just add tax on that income. It can also eat your SALT deduction at the same time. Effectively, every dollar in that phase-out zone costs you more than its bracket suggests.
So before you prepay a state tax bill or assume that property tax payment will save you money federally, check whether there is actually room under your real cap. Paying the tax is not the same as deducting it. We run this calculation on every projection, because for a surprising number of households the answer is “there is no room.”
Your 401(k) Catch-Up Might Not Be Pretax Anymore
Year-end is when we compare what you meant to contribute with what actually went through payroll. Those two numbers are different more often than you would think.
For 2026, the employee 401(k) limit is $24,500. If you are 50 or older and your plan allows it, you can add an $8,000 catch-up. If you turn 60, 61, 62, or 63 this year, the catch-up jumps to $11,250, so your total employee contribution can hit $35,750.
Here is the 2026 change that is quietly messing up people’s projections. If your prior-year wages from the employer sponsoring the plan were over $150,000, your catch-up contributions now have to go in as Roth. Not pretax. Roth. That is a test of your W-2 wages from that one employer, not your total household income.
Roth is fine. We like Roth. But Roth catch-up dollars do not reduce this year’s taxable income, and a projection that assumes every retirement dollar is pretax will overstate your tax savings. We have already caught this on a handful of client projections this fall. The regular $24,500 can still be pretax. Only the catch-up gets forced to Roth.
So check your payroll elections, remaining pay periods, and year-to-date contributions. If you changed jobs this year, add up contributions across both employers, because the limit applies to you, not to each plan. Going over is a headache to unwind.
And do not forget the HSA. For 2026, the limits are $4,400 for self-only coverage and $8,750 for family coverage, plus $1,000 more if you are 55 or older. Employer contributions count toward those limits. Eligibility matters as much as the number. A change in coverage or enrolling in Medicare can shrink what you are allowed to put in, so confirm the permitted amount before you transfer the max.
Look at Your Gains Before You Make Another Trade
A year-end investment review starts with what already happened, not with what you are thinking about doing.
How much gain have you realized? Is it short-term or long-term? Do you have capital losses carried forward from prior years? Do you need to sell more to fund a purchase or trim a concentrated position? Our CFA pulls every lot across every account and we answer those before anyone touches a sell button.
Capital losses offset capital gains. When losses exceed gains, you can deduct up to $3,000 of the leftover against ordinary income, and the rest carries forward. That matters for high earners because a $200,000 loss does not knock $200,000 off your salary this year. It knocks off $3,000 and waits.
Tax-loss harvesting also needs coordination. The wash-sale rule disallows the loss if you buy the same or substantially identical security within 30 days before or after the sale. That includes buying it in your IRA. It includes your spouse buying it. Reviewing one brokerage account and calling it done is how people accidentally blow up a harvest. We check every account in the household, including the ones you forgot about.
And the trade still has to make sense as an investment. Selling just to create a deduction, without a plan for what you own afterward, can leave the portfolio in a worse spot than the tax savings are worth. On the flip side, refusing to sell an oversized position purely to dodge capital gains can leave you holding more risk than your plan can survive.
The tax math is one input. It is never the whole decision.
Charitable Giving Changed in 2026. Plan Accordingly
If you already give, this is the year to think about how much, when, and with what. The rules shifted, and the old “write a check in December” approach leaves money on the table.
Starting in 2026, if you itemize, you can only deduct charitable gifts above a floor of 0.5% of your adjusted gross income. Say a household has $800,000 of AGI and gives $30,000. The floor is $4,000, so only $26,000 is potentially deductible, before any other limits. Not $30,000.
There is a second hit for top-bracket households. Itemized deductions that would offset income in the 37% bracket now only save you 35 cents on the dollar instead of 37. Small percentage, real money at scale.
Both of these push the same direction: bunching. Instead of giving $30,000 every year and losing $4,000 to the floor each time, you give three years’ worth in one year and clear the floor once. We model this against your income, your other deductions, and how much you can actually part with, and we tell you whether bunching beats annual giving for your specific numbers. Sometimes it does not.
What you give with matters too. Donating appreciated stock you have held more than a year to a public charity generally gets you a fair-market-value deduction without ever paying capital gains on the growth. If you have a concentrated position you need to trim anyway, this is often the single most efficient way to do it. Cash and non-cash gifts have different limits and paperwork, and we handle the documentation so the deduction survives an audit.
A donor-advised fund can be the vehicle for all of this. One thing to be clear on: once money goes in, it is legally the charity’s. It is no longer your emergency fund.
The point is to fund the giving you want to do, efficiently. Not to give money away because a deduction exists.
Business Owners: Stop Buying Stuff Just for the Deduction
A profitable year creates a strong urge to go find deductions. We get it. But spending money and improving your financial position are not the same thing, and a lot of December purchases are the first one dressed up as the second.
We start with current business financials and a projection of your personal return, because for most owners those are the same problem. Then we look at retirement-plan funding, purchases you actually need, and the deductions that apply to your specific business.
The qualified business income deduction can be worth up to 20% of eligible income, but it has limits that depend on your industry, your taxable income, the wages you pay, and the property you own. We calculate it from the real numbers, not the headline rate. Plenty of owners assume they get the full 20% and do not.
Retirement plan design is where the big numbers live. A cash balance plan can let a high-earning owner put away far more than a 401(k) alone. It also comes with required annual funding, actuarial work, and admin costs. We only recommend one when the deduction clearly outweighs the commitment, and we have talked clients out of them more than once.
Equipment is the classic December trap. Current law allows 100% bonus depreciation on qualifying property acquired and placed in service after January 19, 2025. But placed in service means in use and ready to go, not ordered, not paid for, not sitting on a loading dock. Timing and qualification both matter, and we confirm both before anyone counts the deduction.
Before accelerating any purchase, ask whether the business needs it, whether now is the right time, and whether the after-tax cost is worth it. A deduction lowers the price of something you needed anyway. It does not make something you did not need free.
What Has to Happen in December vs. What Can Wait
Not everything expires on December 31. But some things do, and some things expire even earlier. Mixing them up is how good plans die.
Before your final 2026 paychecks, fix your withholding and your retirement deferrals. Once the last payroll runs, that money is gone and you cannot get it back. Payroll and plan cutoffs are usually earlier than people think, so we confirm them in November.
By December 31, finish any 2026 charitable gifts and any investment sales you need to recognize gains or losses this year. Stock transfers to a charity or donor-advised fund can take days or weeks to process, and the gift date is when the charity receives it, not when you hit submit. Do not start this on the 28th.
On January 15, 2027, the fourth federal estimated payment for 2026 is due. This covers the final quarter only. It does not retroactively fix an installment you shorted in June.
By the filing deadline, you can still make 2026 IRA and HSA contributions, assuming you are eligible. Some employer retirement plan contributions can go even later, including on extension, depending on the plan. We use that window deliberately, because it lets us fund contributions once the return is nearly final and we know exactly where the numbers land.
That is not every deadline. State rules, special relief, and account-specific requirements can all differ. The point is to treat December 31 as the finish line for decisions that need earlier coordination, not as the day you start thinking about them.
The Tax Plan Is Part of the Financial Plan
A good year-end review leaves you with more than an estimate of what you owe. You should walk away knowing the number, how it gets paid, which moves are worth making, and who is doing each one.
It should also tell you what you decided not to do. Not every deduction is worth chasing. Not every gain should be deferred. Not every retirement dollar gets the same treatment anymore. The right call depends on the whole household, not one line on the return.
At Iarann Wealth, tax planning is built into the financial plan, not bolted on. Our team includes a CFP, an EA, and a CFA, so the projection, the portfolio decisions, the retirement funding, and the business planning all come from one set of numbers. We are not here to replace your accountant. We think you should have a good one, and we work with them directly. What we do is make sure that by the time they prepare the return, the decisions that actually move the number have already been made, on purpose, with the whole picture in view.
The question is not “how do I pay less tax this year?” It is “which decisions leave me in a stronger position after taxes, now and five years from now?” Those are different questions with different answers.
If you had a big year, get a current projection and a specific action list in front of your team before the calendar runs out on you.
This article reflects federal tax rules reviewed as of October 1, 2026, and is intended for educational purposes. It is not individualized investment, tax, or legal advice. State treatment may differ, and eligibility, limitations, and deadlines depend on individual circumstances. The examples are hypothetical and do not represent actual client results. Consult your advisory, tax, and legal professionals before implementing a strategy.
____________________________________________________________________________________________
About Iarann Wealth
At Iarann Wealth, we believe managing wealth isn’t just about numbers—it’s about purpose, clarity, and confidence for the road ahead. Whether you’re building a business, growing your investments, preparing for retirement, or navigating major life decisions, our mission is to help you make smarter financial choices that align with your values and goals.
We serve high-income earners, business owners, tech professionals, and families with comprehensive, relationship-focused financial planning. From tax strategy and cash flow management to retirement, estate, and exit planning—we deliver actionable strategies designed to support your long-term success.
Our Services Include:
- Cash Flow & Investment Planning
- Tax Strategy & Risk Management
- Retirement & Estate Planning
- Education & Insurance Planning
- Business Exit & Asset Protection Strategies
- Real Estate & Major Life Decision Support
We offer transparent pricing through either an Assets Under Management (AUM) model or flat-fee financial planning, providing flexibility to meet your unique financial needs.
This material is for educational purposes and is not individualized investment, tax, or legal advice. The hypothetical illustration is not an actual client experience or a projection of investment performance. Investing involves risk, including loss of principal. Diversification does not guarantee a profit or protect against loss. Consult your advisory, tax, and legal professionals before implementing a strategy.